Guides
Which exposures should food truck insurance policies actually include?
Food truck business insurance without invented prices: the exposures a truck carries that a restaurant does not, the exclusions to hunt for, and certificates.
What to take away
- No page can tell you what a policy will cost. What it can do is show you the exposures a truck carries that a fixed restaurant does not, so you can tell whether a quote actually covers them.
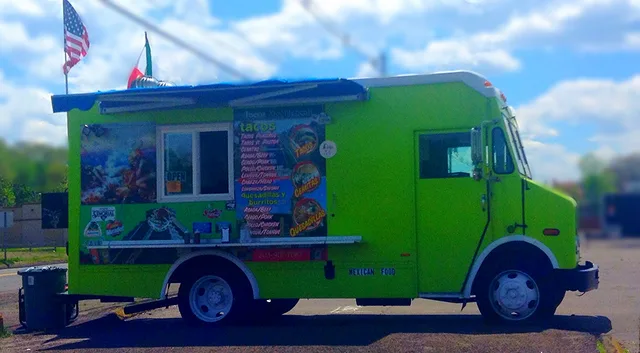
- A truck is a vehicle, a kitchen and a temporary public place at the same time, and those three things are usually insured under different agreements.
- The certificate is the operational document. Event hosts, property owners and commissaries will ask for one with specific wording, and the wording is where deals are lost.
- Read the exclusions before the limits. A generous limit on a cover that excludes your actual operation is worth nothing.
- Talk to a licensed broker who has written mobile food before. Everything below is a preparation exercise for that conversation, not a substitute for it.
Why a price cannot be quoted here
Premiums depend on the details: vehicle, cooking method, whether you fry, staff count, and location. They also depend on claims history and what your bookings require you to carry. Swap the fryer for a griddle or add a second driver, and the calculation changes.
Anyone publishing a number describes one operation somewhere and invites you to assume it is yours.
What is stable across operations is the list of things that can go wrong. That list is worth writing down, because it is what you check a quote against.
The exposures a truck actually carries
Think of the day in four states, because a policy that covers one may say nothing about another.
Four states of the truck day
In transit
- What can go wrong
- Collision, theft, equipment damage
- What responds
- Commercial auto, equipment scheduled
Parked and trading
- What can go wrong
- Trip, awning drop, generator burn
- What responds
- General liability at the site
Food served
- What can go wrong
- Illness or allergic reaction
- What responds
- Products and completed operations
Shut and stored
- What can go wrong
- Fire, vandalism, power-fail spoilage
- What responds
- Property, spoilage or breakdown
| State of the day | What can go wrong | What tends to respond |
|---|---|---|
| In transit | Collision, theft of the vehicle, damage to equipment inside it | Commercial auto, with equipment often needing its own schedule |
| Parked and trading | Someone trips at the queue, an awning drops, the generator burns someone | General liability at the site |
| Food served | Illness or an allergic reaction traced to your product | Products and completed operations, which is not always automatically included |
| Shut and stored | Fire at the yard, vandalism, spoilage when the power fails | Property, plus a separate spoilage or breakdown agreement |
The gap that surprises people is the second row against the first. A commercial auto policy may cover the truck while it is a vehicle and stop mattering the moment it becomes a stall. Ask the broker directly which agreement is responding while the truck is stationary with the window open, and get the answer in writing.
Reading a quote for the exclusions
Work through the quote looking for what is carved out, in this order.
- Cooking method. Some wordings treat deep frying, open flame or solid fuel differently. If you fry, say so before the quote rather than after a claim.
- Fuel. Ask how propane storage and use are treated, and whether the cylinder count or mounting affects cover.
- Location type. Enclosed venues, parking structures, private festivals and public right of way can be treated as different risks.
- Staff. Whether volunteers, family helping out on a busy Saturday, or a driver who is not on payroll are covered.
- Territory and radius. Some policies limit how far from a base address the vehicle operates, which quietly caps your bookings.
- Equipment ownership. Whether a leased fryer or a borrowed trailer is on your schedule at all.
Write the answers next to the premium. A cheaper quote with two of these excluded is not cheaper.
Workers' compensation and the employment side
The moment anyone works for you, a separate obligation appears, and it is set by your state rather than by your insurer. Thresholds, who counts as an employee, and whether owners can opt out all vary.
Ask your state's workers' compensation authority directly, and ask before the first shift, because coverage that starts late does not reach backwards. The wider employment questions that arrive with a first hire are covered in what a new hire has to complete and what you owe them.
What the certificate has to say
Most of your insurance admin will not involve claims. It will be about producing a certificate that satisfies whoever lets you trade. Event organizers, property owners and commissaries commonly want to be named, a specific limit, and notice if the policy lapses.
Collect those requirements early, because a booking confirmed on Tuesday for a Saturday event leaves no time to change a policy.
Build a small table of your recurring sites and what each one asks for. Then check it against what you actually hold once a year rather than once per booking.
Watch for a single venue whose requirement is higher than everyone else's. It is often cheaper to hold that level all year than to endorse the policy every time.
Those requirements are also a line item, so they belong in the financial section every lender and landlord reads, not as a first-season surprise.
Where the regulators come into it
Insurance does not make an operation legal, and legality does not make it insured, but the two interact. An authority that can suspend your permit can stop your revenue whether or not anything is damaged, and business interruption cover is priced on that risk.
The FDA's directory of the agencies that administer retail food regulation is where you identify the body that holds that power in each place you trade. Do that before deciding whether interruption cover is worth buying.
The same logic applies to the food process itself. The model food code your authority adapts describes the handling, holding and cross contamination controls that a products liability claim will be judged against. Your temperature logs and cleaning records are the evidence, which is why the daily discipline described in the permit and inspection guide is also an insurance asset.
Accessibility sits in a third category. The Justice Department's guide for small businesses says obligations are assessed against how customers reach the service and what is readily achievable to change. That is a compliance question rather than an insured peril.
Treating accessibility as something a policy handles is a common and expensive misreading. It belongs with the rest of the office by office permit questions.
Common questions
Do I need insurance before I have a permit?
Often yes, in practice. Commissaries, landlords and event hosts tend to ask for a certificate before they will confirm anything, and some permit applications ask for evidence of cover. Ask each of them what they require at the point you first contact them, so you are not buying cover twice.
Is my personal auto policy enough while I am just testing the idea?
Assume not. Personal auto wordings commonly exclude business use, and a truck built for commercial cooking is unlikely to sit inside one at all. Ask the question of your own insurer in writing before you drive to a first event, because an answer given in a phone call is hard to rely on later.
What limits should I carry?
Whatever your obligations require, plus your own judgment about what a serious claim would look like. Contracts and venues will set a floor. Above that floor the decision is about how much of your own assets you want standing behind the operation, and that is a conversation for a licensed broker who can see your whole position.
How does adding a second truck change things?
More than proportionally, usually, because a fleet is rated differently from a single vehicle and because a second unit often means new drivers, new locations and sometimes a new jurisdiction. Raise it with the broker before you buy, and read it alongside the growth decisions that come with a second unit.